 M-FILES
Representative Car: Business Necessity or Costly Indulgence!?
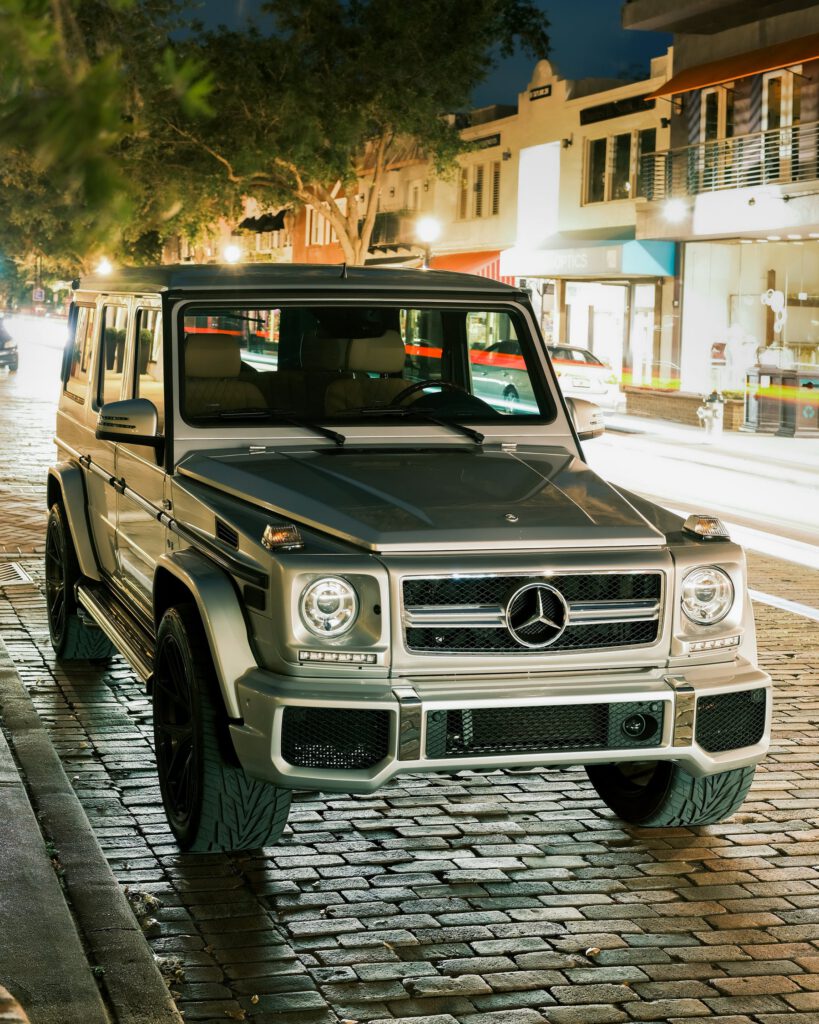
In practice, we regularly encounter questions about what a representative car is, whether there are opportunities to purchase it with discounts, and if there are any ways to circumvent the established acquisition procedures!? What is the reality!?
According to the Republic of Latvia law “On Corporate Income Tax,” the value of a representative vehicle is determined by its acquisition value or accounting value throughout the vehicle’s entire period of use, taking into account the higher of the two values. This means that an acquired vehicle never loses its status as a representative vehicle. Furthermore, if it initially did not have representative vehicle status, it can acquire it later. The accounting value includes the purchase price (minus any received discounts), non-deductible taxes and fees associated with the purchase, as well as expenses directly related to the vehicle’s delivery to the place of use and its preparation for the intended purpose, incurred until the vehicle is ready for this purpose. Expenses related to the vehicle’s mandatory annual maintenance are not included in the accounting value.
The law also specifically stipulates that the acquisition value of a representative vehicle is determined by also considering the costs of improvements made within a 12-month period after its acquisition. Therefore, there are practically no possibilities to circumvent the established procedure for reducing the vehicle’s value, and the vehicle’s value for VAT and CIT purposes can no longer be split or reduced by later issuing invoices for installed navigation and cruise control systems, music systems, displays, or similar items that are clearly understood to have been mounted on the car later, even if that is not actually the case.
In the case of a leased car, the basis for determining the value of a representative vehicle is the car’s value specified in the lease agreement, or if not specified, the car’s value indicated in the insurance policy is taken as the basis.
The value of a representative vehicle is also not reduced by the fact that an employee or board member of the company covers the excess value without VAT, nor is the most common mistake made in situations where an old car is given to the car seller as a down payment and a mutual offset is performed.
If you need daily support in managing full-cycle financial accounting and have missed these or other accounting-related questions due to busyness, and it is important to you in the long term, feel free to contact us right here on the website and receive favorable terms for starting cooperation with our accounting office.
Our team will rush to your aid!
By applying for the service on our website, you will receive a free solution
for transferring accounting data to facilitate starting cooperation with us. As well as
a 2-hour free consultation on how to improve your business operations!